 Akash Kumar
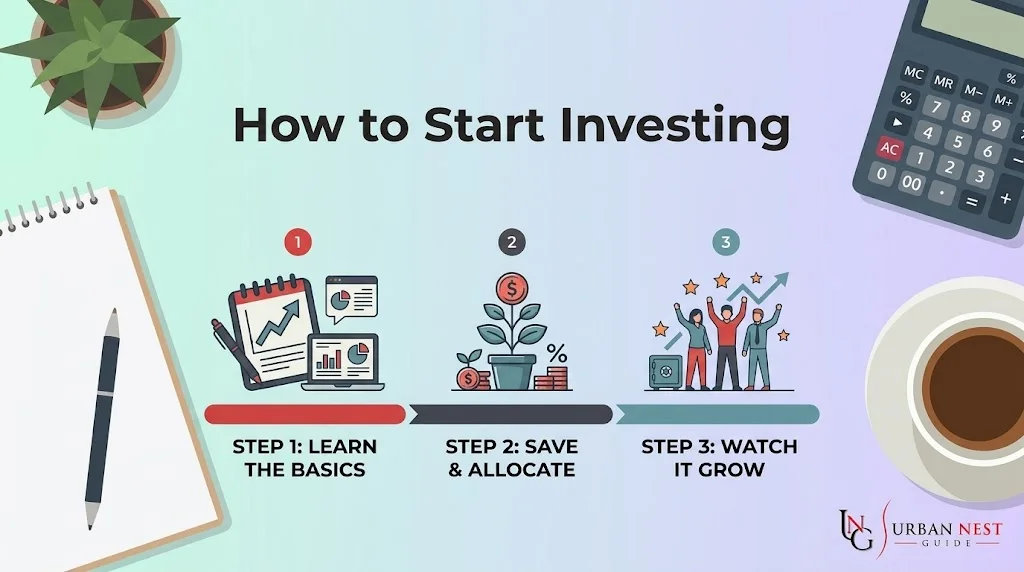
Investing sounds like something reserved for rich people in suits shouting on a trading floor.
It is not. The truth is that anyone can start investing today, often with just a few dollars, and the earlier you begin the better.
If you have ever felt confused or intimidated by the whole thing, this guide is for you. We will walk through exactly how to start investing as a beginner, in plain language, one step at a time.
By the end, you will understand what investing actually is, how much money you need to begin (spoiler: far less than you think), and the simple, proven path most successful everyday investors follow. No jargon, no hype, no pressure.
Key Takeaways
What Is Investing, Really?
Investing simply means putting your money to work so it can grow over time. Instead of letting cash sit in a checking account losing value to inflation, you buy assets, such as small pieces of companies, that tend to increase in value over the years.
The magic ingredient is compound interest, which is when your money earns returns, and then those returns earn returns of their own. Over decades, this snowball effect can turn modest, regular contributions into a serious amount of money. That is why starting early matters so much, even if you can only invest a little.
Step 1: Get Your Financial Foundation Ready
Before you invest a single dollar, two things should be in place. First, a starter emergency fund so an unexpected bill does not force you to sell your investments at a bad time. Second, pay off any high interest debt, like credit cards. Paying off a card charging 21% is a guaranteed 21% return, which beats almost any investment. Not sure how to tackle it? Our guide on the debt snowball versus avalanche methods breaks it down.
Once you have a small cushion and your expensive debt is under control, you are ready to invest with real peace of mind.
Step 2: Decide How Much You Can Invest
Here is the good news: you do not need thousands of dollars. Thanks to fractional shares, you can buy a slice of a company or fund for as little as $1. What matters far more than the amount is the habit of investing regularly.
A simple approach many beginners use is to invest a fixed percentage of their income, or whatever they can spare after covering needs. If you follow the 50/30/20 budgeting rule, your investing money comes out of the 20% earmarked for savings and financial goals. Even $50 a month, invested consistently, adds up to a meaningful sum over the years.
Step 3: Choose the Right Account
You invest through an account, and picking the right type can save you a lot in taxes. Here are the main options for beginners.
| Account type | Best for | Why it helps |
| 401(k) | Anyone with an employer match | Free money from your employer, plus tax benefits |
| Roth IRA | Long-term, tax-free growth | You pay tax now, withdraw tax-free in retirement |
| Traditional IRA | Lowering taxes today | Contributions may be tax-deductible now |
| Taxable brokerage | Flexible, no limits | Invest any amount, withdraw anytime |
If your job offers a 401(k) with a match, start there and contribute at least enough to get the full match; it is an instant return you should never leave on the table. After that, a Roth IRA is a fantastic beginner choice for its tax-free growth. If you want something with no limits and full flexibility, a regular brokerage account works too.
Step 4: Pick What to Invest In
This is where beginners freeze, but it is simpler than it looks. For most people just starting out, a low cost index fund is the ideal first investment. Instead of trying to pick winning stocks, an index fund lets you own a tiny piece of hundreds of companies at once, such as the 500 largest US companies in an S&P 500 fund. That gives you instant diversification, which simply means you are not putting all your eggs in one basket.
Why not pick individual stocks? Because even most professional investors fail to beat a simple index fund over the long run. Starting with a broad, low cost fund keeps your risk lower and your life simpler. You can always explore other investments later once you are comfortable.
For trustworthy, unbiased basics on different investment types, the government-run Investor.gov site is an excellent, ad-free resource worth bookmarking.
A Quick Word on Stocks, Bonds, and Other Options
As you get comfortable, it helps to know the main things you can actually invest in, in plain terms. Stocks are small pieces of ownership in a company; they offer the highest long-term growth but bounce around more. Bonds are essentially loans you make to a government or company that pay you interest; they are steadier but grow more slowly. Funds, like index funds and ETFs, bundle many stocks or bonds together so you get instant diversification in a single purchase, which is exactly why they are so beginner-friendly.
You will also hear about other options like real estate, dividend stocks, and even cryptocurrency. These can have a place once your foundation is solid, but as a beginner you do not need them to succeed. A simple portfolio of broad index funds has quietly made more everyday people wealthy than any exotic strategy. Master the basics first, then explore from a position of strength.
Step 5: Automate and Stay Consistent
The final step is the secret to long-term success: set up automatic monthly investments and then mostly leave them alone. Investing the same amount every month, no matter what the market is doing, is a strategy called dollar cost averaging. It removes emotion and stops you from trying to time the market, which almost nobody does well.
When the market drops, it is tempting to panic and sell. Resist that urge. Downturns are normal, and history shows the market has always recovered and grown over long periods. The investors who win are usually the ones who stay calm, keep contributing, and think in decades, not days.
How Compound Growth Turns Small Money Into Big Money
Let us make the case for starting early with real numbers, because this is the part that motivates people more than anything. Imagine you invest just $200 a month starting at age 25 and earn the stock market’s long-term average of around 7% after inflation. By age 65, you would have contributed $96,000 of your own money, but your account would be worth roughly $525,000. The extra $429,000 is pure compound growth, money your money earned for you.
Now imagine your friend waits until age 35 to start the same $200 a month. By 65, they end up with only about $245,000, less than half, despite investing for 30 years instead of 40. That ten-year head start more than doubled the result. This is why the single most powerful move in investing is simply to begin, even with a small amount. You can always increase your contributions later; you can never get back lost time.
| Start age | Monthly amount | Value at 65 (about 7%) |
| 25 | $200 | around $525,000 |
| 35 | $200 | around $245,000 |
| 45 | $200 | around $105,000 |
Understanding Risk and Your Time Horizon
A quick word on risk, because it trips up a lot of beginners. In investing, risk and reward go hand in hand. Stocks can swing up and down sharply in the short term, but over long periods they have historically delivered the strongest growth. Safer options like bonds move more gently but grow more slowly. The key is matching your investments to your time horizon, which is just a fancy phrase for when you will need the money.
If you are investing for retirement decades away, short-term dips barely matter; you have plenty of time to recover, so you can lean heavily toward stocks. If you need the money in a couple of years, it does not belong in the stock market at all; keep it in savings instead. A common beginner approach is to hold mostly stock index funds while you are young, then gradually shift some money into bonds as you get closer to needing it. You do not have to overthink this; even a single diversified index fund handles a lot of it for you.
Common Beginner Investing Mistakes to Avoid
- Waiting for the perfect time. There is never a perfect moment. The best time to start was years ago; the second best is today.
- Trying to get rich quick. Chasing hot tips and meme stocks is gambling, not investing. Slow and steady wins.
- Investing money you will need soon. Only invest money you can leave alone for at least five years.
- Ignoring fees. High fees quietly eat your returns. Stick to low cost funds with small expense ratios.
- Checking your account constantly. Daily monitoring leads to anxiety and bad decisions. Set it and forget it.
FAQs
How much money do I need to start investing?
You can start investing with as little as $1 thanks to fractional shares offered by most brokerages and investing apps. What matters more than the starting amount is investing consistently over time, even small amounts like $50 a month.
What is the best investment for beginners?
For most beginners, a low cost index fund, such as one that tracks the S&P 500, is an excellent first investment. It spreads your money across hundreds of companies, which lowers risk, and it has historically delivered strong long-term returns.
Should I pay off debt or invest first?
Pay off high interest debt like credit cards before investing heavily, since eliminating a 20% interest charge is a guaranteed return. Always contribute enough to get any employer 401(k) match first, though, because that is free money.
Is investing risky for beginners?
All investing carries some risk, but you can manage it by diversifying with index funds, investing for the long term, and only using money you will not need soon. Historically, staying invested through ups and downs has rewarded patient investors.
Trusted resources:Investor.gov, U.S. Securities and Exchange Commission, and FINRA.
Disclaimer: This article is for general education, not investment advice. All investing involves risk. Consider your own situation or consult a licensed professional before investing.
About The Author